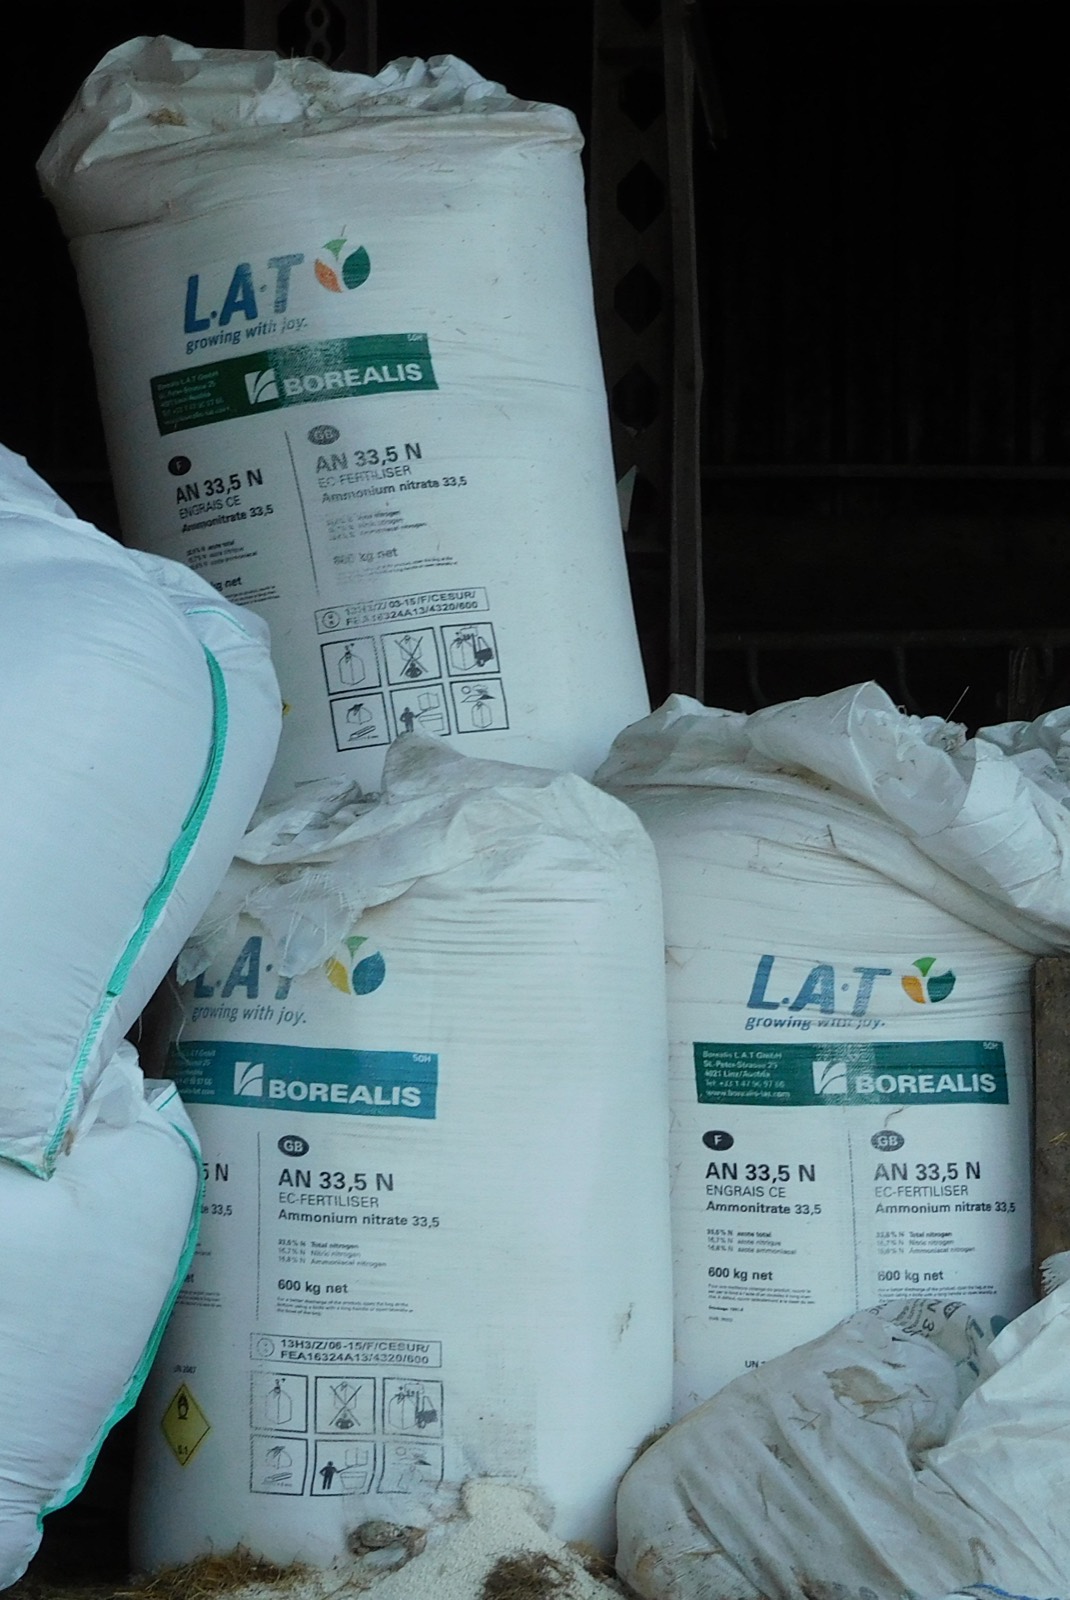
Fertilizer trade has a reputation for being a government business, all tenders and subsidies and state buying agencies. Half of that is true. The other half is a large, fast-moving private market of blenders, distributors and agri-input wholesalers who buy in 5,000 to 50,000 tonne lots and never appear in a tender announcement. Most exporters chase the first half and ignore the second.
The 30-second version
- India is the largest urea importer at roughly 9.5 million tonnes, worth about US$4.2 billion.
- Brazil follows at 7.7 million tonnes, then the United States, Australia and Türkiye.
- Indian urea imports more than doubled, up 120.3% to 7.17 million tonnes, while domestic output slipped 3.7% to 19.75 million tonnes.
- In April to June 2026 India took 2.51 million tonnes of urea and 0.71 million tonnes of DAP.
- Brazil has been substituting: 1.75 million tonnes of ammonium sulfate against 1.4 million tonnes of urea in the first four months of 2026.
The demand map
Five buyers dominate the traded urea market, and each is driven by something different. India buys to cover a structural production gap. Brazil buys to feed a soybean and corn cycle that is expanding faster than its domestic nitrogen capacity. The United States buys seasonally around planting. Australia buys because it has almost no domestic urea production. Türkiye buys for both domestic agriculture and as a processing and re-export point into neighbouring markets.
The timing differences matter more than the volumes. Indian demand clusters around the kharif and rabi seasons and is heavily tender-driven. Brazilian buying front-loads before the safrinha planting window. North American demand spikes in spring. An exporter who understands only one of these cycles has a business that is idle for two quarters a year.
Why India's import bill doubled
Two things moved at once. Domestic urea production fell 3.7% to 19.75 million tonnes, and consumption did not fall with it. The gap went straight to imports, which jumped 120.3% to 7.17 million tonnes from 3.26 million tonnes the year before, as Global Agriculture reported.
The DAP picture is tighter still. Phosphate supply has been constrained globally, and India's DAP intake of 0.71 million tonnes in the June quarter sits against a demand base far larger than that. For exporters with phosphate availability, India is the most price-insensitive buyer in the market right now, which is not a sentence you get to write often.
Fertilizer demand does not disappear when prices rise. It moves to a cheaper nutrient. Watch the substitution, not the price.
The substitution story in Brazil
Brazil is the clearest example of that. In the first four months of 2026 Brazilian buyers took 1.75 million tonnes of ammonium sulfate against 1.4 million tonnes of urea, because ammonium sulfate delivered nitrogen more cheaply at prevailing prices. Meanwhile roughly 1.24 million tonnes of urea sat stranded in the Persian Gulf as buyers stepped back from the price level India's tendering had set, per Fertilizer Daily.
If you sell nitrogen, that is the single most useful behaviour to track. A buyer that has switched product once will switch again, in either direction, and the switch shows up in shipment records weeks before it shows up in commentary.
Finding the buyers who are not in the tenders
State agencies publish. Private importers do not. The private layer is where most exporters can actually win business, because it is not decided by a sealed-bid process, and it looks like this in the data:
- Repeat mid-size lots. Regular 10,000 to 30,000 tonne arrivals into secondary ports usually means a private blender or distributor rather than a state buyer.
- Multiple origins in one year. A buyer sourcing from Oman, Egypt and Russia in the same season is running a commercial procurement desk and will take a call.
- Granular versus prilled split. The product form a buyer consistently takes tells you whether they serve mechanised broadacre farming or smallholder distribution, which changes your entire pitch.
- Port of discharge. Inland distribution economics mean a buyer discharging at one port almost never switches, so match your freight to their port rather than to your own convenience.
Where the 2026 opportunity sits
India's phosphate gap is the largest single opening, and it is not closing this year. Brazil's nitrogen substitution creates an opening for ammonium sulfate and blended NPK suppliers who can move quickly. Türkiye deserves more attention than it gets, both as an end market and as a re-export platform into the Caucasus and Central Asia. Our Turkish importer guide covers how that market is structured, and the agrochemical buyer guide covers the adjacent crop protection trade, which shares most of the same customers.
Vessel size and port constraints decide who can bid
Fertilizer is a bulk trade, and the physical constraints at the discharge port frequently matter more than the price you can offer.
Handysize and Supramax vessels dominate, but the binding limits are draft, berth availability and discharge rate. A port that can only take 25,000 tonne parcels puts you at a structural disadvantage against a supplier who can economically break bulk, regardless of your ex-works price. A port with a slow discharge rate adds demurrage risk that someone has to price, and in most contracts that someone is the seller.
Bagging is the other constraint worth checking early. Some markets take product in bulk and bag inland; others require bagged delivery, which changes your loading operation, your freight economics and your lead time. Indian and Brazilian buyers handle bulk at scale. Many African and Southeast Asian buyers do not.
Ask about vessel size, draft and bagging before quoting. It is a short conversation that saves quoting into a lane you cannot serve.
How ShipScout helps
Tender results are public and always late. Shipment records are neither. ShipScout gives you 11B+ shipment records across 240+ countries so you can:
- List fertilizer importers by country and product, ranked by actual tonnage rather than by reputation.
- See which origins each buyer uses and how that mix has shifted over the last four quarters.
- Catch substitution early, when a nitrogen buyer starts taking a different nutrient, which is the moment their supply list is open.
- Pull decision-maker contacts where available for the private importers who never appear in a tender notice.
Start a free trial and pull the importer list for your product and season.
See who’s importing urea and DAP right now.
ShipScout turns 11B+ shipment records across 240+ countries into a live list of verified buyers and suppliers, ranked by volume, with the contacts to reach them. Create a free account and run your first search in minutes.
Start your free trial →